Berkshire’s (BRK.A) recent activity is discussed.
Disclosure (“none” means no position):None

Visit the ValuePlays Bookstore for Great Investing Books

This work is licensed under a Creative Commons Attribution 2.5 License.
Berkshire’s (BRK.A) recent activity is discussed.
Disclosure (“none” means no position):None
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
Thursday’s Picks
Jeff Macke likes Boeing (BA) $78.6.
Guy Adami recommends AMR Corp. (AMR) $9.17 for a short covering rally.
Pete Najarian thinks investors should buy puts in Pilgrim’s Pride (PPC) $19.4
Tim Seymour prefers shorting Mechel (MTL) $142.88 and buying it back at $130.
Wednesday’s Results
Guy Adami recommends US Bancorp (USB) $32.79 Close $32.45 LOSS
Pete Najarian prefers Myriad Genetics (MYGN) $41.0 Close $40.35 LOSS
Both Jeff Macke and Karen Finerman think the Financial Select Sector SPDR (XLF) $26.22 is a buy. Close $25.78 LOSS
2008 Records:
Brian Schaeffer= 0-1
Carter Worth= 0-1
Jon Najarian= 4-1
Jeff Macke= 25-19-1
Tim Seymore= 14-8
Guy Adami= 24-23
Pete Najarian= 27-21
Karen Finerman= 20-24-1
Joe Terrenova= 1-1
2007 Results (Since 6/21):
Guy Adami= 58-46 = 56%
Jeff Macke= 60-40 = 60%
Pete Najarian= 49-41 = 54%
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
“Save your frightened song for when there is really something wrong! Don’t cry ‘wolf’ when there is NO wolf!” The Boy Who Cried Wolf , Aesop’s Fables
Another year has gone by and the latest hurricane forecast is out. It is great because it is an easy post. I get to cut and past last years hurricane post because the outlook is the same as it has been since the turn of the century.
Current forecast from Colorado Sate: “We foresee a well above-average Atlantic basin tropical cyclone season in 2008. We have increased our seasonal forecast from our initial early December prediction. We anticipate an above-average probability of United States major hurricane landfall.” also “We estimate that 2008 will have about 8 hurricanes (average is 5.9), 15 named storms (average is 9.6), 80 named storm days (average is 49.1), 40 hurricane days (average is 24.5), 4 intense (Category 3-4-5) hurricanes (average is 2.3) and 9 intense hurricane days (average is 5.0). The probability of U.S. major hurricane landfall is estimated to be about 135 percent of the long-period average.”
Why do they do this? We all know it is guess work…
Last years post:
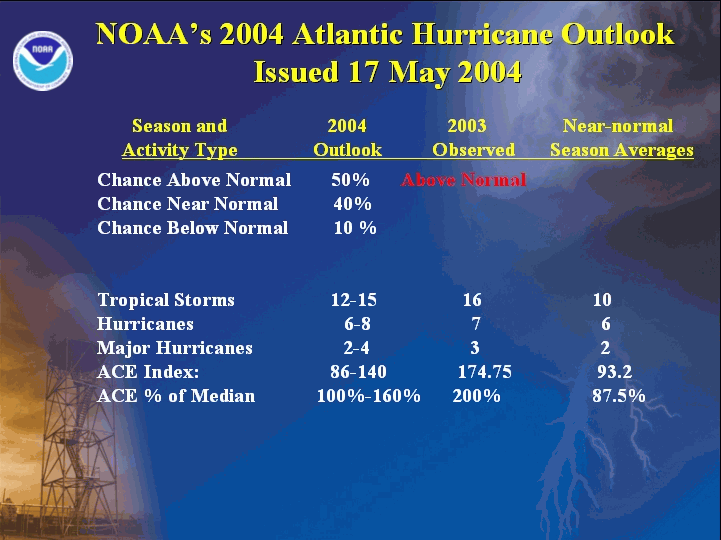
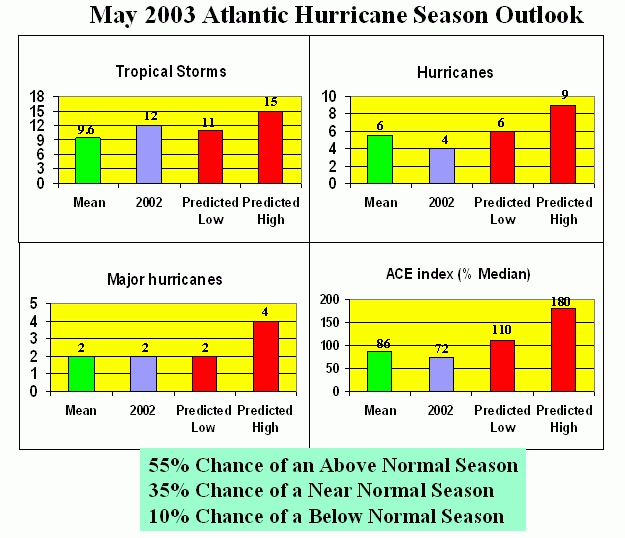
In case you missed it today and I think you would have had to have had no contact with the outside world in order to, researchers once again predicted an above normal hurricane season. Excuse me while I yawn at this one. In order to fully understand the true depth of my ambivalence, one must take a walk down memory lane and look at past hurricane forecasts. I am only going to go back the last 5 seasons here just to make a point:
The real question here the talking heads on TV ought to be asking is: “when haven’t they predicted an active season”? The answer? I do not know because the NOAA archives only go back to 1999 and only 2001 predicted a benign forecast of “normal to slightly above normal” hurricane activity. Every other year has featured an apocalyptic forecast. What do we as investors do then? This answer is easy, nothing. Meteorologists cannot even tell me with any significant accuracy if it is going to rain or not this weekend yet we are supposed to believe they can now predict a certain number of storms are going to form off the coast of Africa over 3,000 miles away and hit the states during the next 6 months? No way…..It is a fools bet. One also has to notice as they read the forecasts: “Why are they all basically the same?” 12-15 storms, 6-8 hurricanes, 2-4 majors. If every forecast is for the same number of storms, isn’t that then, “normal”?
The bottom line is that it has become painfully apparent we are always going to get a forecast that is for “above normal” hurricane activity. Worrying about it or trying to adjust your portfolio for this presumed alleged event in April is a colossal waste of time.
The phrase “to cry wolf“, derived from the fable, refers to the act of persistently raising the alarm about a non-existent threat, with the implication that the person who cried wolf would not be taken seriously should a real emergency take place. It can also be used to describe an alarm system that regularly goes off falsely, causing it not to be believed when a real emergency occurs.
Forecasters beware…
Disclosure (“none” means no position):
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
The story here isn’t the fact Citi (C) is selling $12 billion of loans and what effect that has on its balance sheet and earnings. The story is that there actually is a buyer.
Citigroup had $43 billion worth of leveraged loans on its books at the end of the fourth quarter and is allegedly selling $12 billion of that to private-equity firms Apollo Management, TPG and Blackstone Group (BX).
This comes on the heals of a proposed plan at UBS (UBS) that would also either sell loans to investors or place them in a subsidiary to then spin.
The news here isn’t what the loans sold for (90 cents on the dollar) or what that might mean for the current quarter in term of write-offs to earnings. The news is that for the first time, someone is actually willing to buy the stuff. It was only a few months ago Citigroup issued dilutive preferred equity (See Washington Mutual for the latest round (WMU)) at near double digit interest rates to accomplish the same thing, restore liquidity to the balance sheet.
There were at that time no buyers for the loans as there seemed no bottom in sight to the write-downs.
If nothing else, we can now surmise that the values of these assets are now to the point that they are going to now have a market value to them based on what is now actually selling rather than the “model based” valuations we have been seeing. This will give the market some confidence as to how to value what is left.
Disclosure (“none” means no position):Long C, None
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
The story here isn’t the fact Citi (C) is selling $12 billion of loans and what effect that has on its balance sheet and earnings. The story is that there actually is a buyer.
Citigroup had $43 billion worth of leveraged loans on its books at the end of the fourth quarter and is allegedly selling $12 billion of that to private-equity firms Apollo Management, TPG and Blackstone Group (BX).
This comes on the heals of a proposed plan at UBS (UBS) that would also either sell loans to investors or place them in a subsidiary to then spin.
The news here isn’t what the loans sold for (90 cents on the dollar) or what that might mean for the current quarter in term of write-offs to earnings. The news is that for the first time, someone is actually willing to buy the stuff. It was only a few months ago Citigroup issued dilutive preferred equity (See Washington Mutual for the latest round (WMU)) at near double digit interest rates to accomplish the same thing, restore liquidity to the balance sheet.
There were at that time no buyers for the loans as there seemed no bottom in sight to the write-downs.
If nothing else, we can now surmise that the values of these assets are now to the point that they are going to now have a market value to them based on what is now actually selling rather than the “model based” valuations we have been seeing. This will give the market some confidence as to how to value what is left.
Disclosure (“none” means no position):Long C, None
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
Whitney Tilson of T2 Partners discusses housing…..
Here is the link, you need to sign up but it is painless and there is no spamming from the registration.
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
Phones, Xbox, Oil, Guilt
– I had no idea this number was so low..
– Were is Blockbuster (BBI)?
– The answer here is easy. LET THEM DRILL
– He has been the most vocal former Fed Head ever…….me think he doth protest too much.
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
Phones, Xbox, Oil, Guilt
– I had no idea this number was so low..
– Were is Blockbuster (BBI)?
– The answer here is easy. LET THEM DRILL
– He has been the most vocal former Fed Head ever…….me think he doth protest too much.
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
Early reports are that response to Stabucks (SBUX) social site mystarbucksidea.com has been positive.
About 300 suggestions were posted in the first hour after the shareholders meeting, which drew a crowd of 6,000 and by the end of the week, more than 100,000 votes had been cast. An algorithm built into MyStarbucksIdea pushes the most popular ideas to the top by factoring in the number of votes, how recently votes are cast and the volume of comments an idea has generated.
While this does show Starbucks is “listening” and could lead to the discovery of the next “big idea”, the concept is fraught with risk. For instance, the first ideas Starbucks promised to enact based on customers’ ideas were ones it had already made: to offer free wireless Internet access in stores and rewards through its loyalty car. So, to date they really have not enacted anything based on customers needs or desires.
Here is where the potential downfall comes in. As the site gains in popularity, and I think it will, the hard core users will dominate the site. That will lead to their ideas also taking prominence on it. Their ideas may benefit their demographic but may not be what is best for the company, trying to serve people at 14,000 locations. Starbucks needs to appeal to a broad range of people, not just those willing to dedicate hours a day trying to push a limited agenda.
Can anyone envision a scenario where a competitor hires a team of folks just to jam the site with ridiculous ideas simply to distract management? I am not suggesting McDonalds (MCD) would do that but I can see thousands of smaller competitors jumping in, or enacting the ideas there and then saying “at least we are listening to you”.
Should these folks then feel “ignored”, the site could morph into a very real company sponsored soapbox of anger. In this case, what was designed as a wonderful idea sharing platform, could become an obstacle to constructive dialogue as to the company’s future. Ignored ideas will then be held up to the “what if you had listened to this” scenario should results not satisfy investors. This is very bad…it illicits second guessing.
Marv Levy, the only coach on the history of the NFL to lead a team to the Super Bowl 4 consecutive times once said, “If you spend too much time listening to the fans, you’ll soon find yourself sitting with them.” A corollary to that could be “do not let the inmates run the asylum.”
Starbucks is in an odd position. They almost have to do the site because they have so lost touch with their consumer it may be the only way for them to understand what is going on out there. I guess any ideas posted there really can’t be much worse than anything coming out of Seattle in the last year and a half. But, unless the site is managed to perfection, it may end up backfiring in a very big way…
Can anyone imagine Berkshire’s (BRK.A) Warren Buffett starting a site so shareholders could give him ideas in what to invest in? Yea…me either..
Disclosure (“none” means no position):Long MCD, None
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
Early reports are that response to Stabucks (SBUX) social site mystarbucksidea.com has been positive.
About 300 suggestions were posted in the first hour after the shareholders meeting, which drew a crowd of 6,000 and by the end of the week, more than 100,000 votes had been cast. An algorithm built into MyStarbucksIdea pushes the most popular ideas to the top by factoring in the number of votes, how recently votes are cast and the volume of comments an idea has generated.
While this does show Starbucks is “listening” and could lead to the discovery of the next “big idea”, the concept is fraught with risk. For instance, the first ideas Starbucks promised to enact based on customers’ ideas were ones it had already made: to offer free wireless Internet access in stores and rewards through its loyalty car. So, to date they really have not enacted anything based on customers needs or desires.
Here is where the potential downfall comes in. As the site gains in popularity, and I think it will, the hard core users will dominate the site. That will lead to their ideas also taking prominence on it. Their ideas may benefit their demographic but may not be what is best for the company, trying to serve people at 14,000 locations. Starbucks needs to appeal to a broad range of people, not just those willing to dedicate hours a day trying to push a limited agenda.
Can anyone envision a scenario where a competitor hires a team of folks just to jam the site with ridiculous ideas simply to distract management? I am not suggesting McDonalds (MCD) would do that but I can see thousands of smaller competitors jumping in, or enacting the ideas there and then saying “at least we are listening to you”.
Should these folks then feel “ignored”, the site could morph into a very real company sponsored soapbox of anger. In this case, what was designed as a wonderful idea sharing platform, could become an obstacle to constructive dialogue as to the company’s future. Ignored ideas will then be held up to the “what if you had listened to this” scenario should results not satisfy investors. This is very bad…it illicits second guessing.
Marv Levy, the only coach on the history of the NFL to lead a team to the Super Bowl 4 consecutive times once said, “If you spend too much time listening to the fans, you’ll soon find yourself sitting with them.” A corollary to that could be “do not let the inmates run the asylum.”
Starbucks is in an odd position. They almost have to do the site because they have so lost touch with their consumer it may be the only way for them to understand what is going on out there. I guess any ideas posted there really can’t be much worse than anything coming out of Seattle in the last year and a half. But, unless the site is managed to perfection, it may end up backfiring in a very big way…
Can anyone imagine Berkshire’s (BRK.A) Warren Buffett starting a site so shareholders could give him ideas in what to invest in? Yea…me either..
Disclosure (“none” means no position):Long MCD, None
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
The devil is always in the details……..
Circuit City (CC) reported fiscal fourth quarter (Feb.) earnings of $0.10 per share, excluding non-recurring items, $0.17 better than the First Call consensus that called for a loss of $0.07. Revenues fell 7.7% year-over-year to $3.65 billion versus the $3.79 billion consensus estimate. GAAP EPS was $.03 a share vs a loss vs $.04 last year. Great right? Look closer….
I like to look at the results from “continuing operations”. It gives me the best snapshot as to the health of the operating business before the accountants and tax collectors get in there and muddle the picture. That being said, in 2007 CC posted a Q4 profit if $27 million from operations. But, in the same quarter of 2008, that plummeted to a LOSS of $2.7 million. So, how did CC then post a profit in its press release?
“For the fourth quarter of fiscal 2008, the company recorded an income tax benefit of $7.3 million. For the fourth quarter of fiscal 2007, income tax expense was $34.3 million.”
There you have it, the reason for both the loss last years and this years gains. The illusion is that last year was worse than this but the reality is the opposite. Operations have deteriorated markedly with same store sales plummeting 11%, margins shrinking and results from operations decimated. Yet, due to a nifty tax benefit, results look nice to the naked eye…
The bottom line is despite what management may say, operationally, the company is deteriorating, fast.
Here is a pdf of the full release:
Disclosure (“none” means no position):None
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
The devil is always in the details……..
Circuit City (CC) reported fiscal fourth quarter (Feb.) earnings of $0.10 per share, excluding non-recurring items, $0.17 better than the First Call consensus that called for a loss of $0.07. Revenues fell 7.7% year-over-year to $3.65 billion versus the $3.79 billion consensus estimate. GAAP EPS was $.03 a share vs a loss vs $.04 last year. Great right? Look closer….
I like to look at the results from “continuing operations”. It gives me the best snapshot as to the health of the operating business before the accountants and tax collectors get in there and muddle the picture. That being said, in 2007 CC posted a Q4 profit if $27 million from operations. But, in the same quarter of 2008, that plummeted to a LOSS of $2.7 million. So, how did CC then post a profit in its press release?
“For the fourth quarter of fiscal 2008, the company recorded an income tax benefit of $7.3 million. For the fourth quarter of fiscal 2007, income tax expense was $34.3 million.”
There you have it, the reason for both the loss last years and this years gains. The illusion is that last year was worse than this but the reality is the opposite. Operations have deteriorated markedly with same store sales plummeting 11%, margins shrinking and results from operations decimated. Yet, due to a nifty tax benefit, results look nice to the naked eye…
The bottom line is despite what management may say, operationally, the company is deteriorating, fast.
Here is a pdf of the full release:
Disclosure (“none” means no position):None
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
We have all read about the Fed minutes released yesterday and the song out there is pretty similar. We could be or are in or about to be in a recession. In other words, growth has slowed. No kidding. As I read it, something at the end struck me.
The vote the recent rate cut was 8-2. Here is the dissent.
“Fisher and Plosser dissented because, in light of heightened inflation risks, they favored easing policy less aggressively. Incoming data suggested a weaker near-term outlook for economic growth, but the Committee’s earlier policy moves had already reduced the target federal funds rate by 225 basis points to address risks to growth, and the full effect of those rate cuts had yet to be felt. While financial markets remained under stress, the Federal Reserve had already taken separate, significant actions to address liquidity issues in markets. In fact, Mr. Fisher felt that focusing on measures targeted at relieving liquidity strains would improve economic prospects more quickly and lastingly than would further reductions in the federal funds rate at this point; he believed that alleviating these strains would increase the efficacy of the earlier rate cuts. Both Messrs. Fisher and Plosser were concerned that inflation expectations could potentially become unhinged should the Committee continue to lower the funds rate in the current environment. They pointed to measures of inflation and indicators of inflation expectations that had risen, and Mr. Fisher stressed the international influences on U.S. inflation rates. Mr. Plosser noted that the Committee could not afford to wait until there was clear evidence that inflation expectations were no longer anchored, as by then it would be too late to prevent a further increase in inflation pressures.”
This goes back to what I said the other day. The best thing perhaps for the economy at this time may be holding rates steady to stop the fall of the dollar. The effect of that would be felt immediately at the pump and in the supermarket. Aside from that, with some clarity surrounding the dollar, commodity markets would then be forced to take its continued expected decline out of the pricing equation. To the contrary, to then price in an increase in the dollar would cause a immediate contraction in commodity prices..
This now looks to be the best course of action.
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
Upgrades
Nutrisystem (NTRI)- Boenning & Scattergood Market Underperform » Market Perform
Energy Transfer (ETP)- UBS Neutral » Buy
Pacific Sunwear (PSUN)- Wachovia Mkt Perform » Outperform
NuStar GP Hldgs (NSH)- Citigroup Hold » Buy
Enterprise GP Holdings (EPE)- Citigroup Hold » Buy
Corning (GLW)- RBC Capital Mkts Sector Perform » Outperform
Intevac (IVAC)- Brean Murray Hold » Buy
Kinetic Concepts (KCI)- Wachovia Mkt Perform » Outperform
Seaspan (SSW)- Wachovia Mkt Perform » Outperform
MetroPCS (PCS)- Wachovia Mkt Perform » Outperform
Metabasis Therapeutics (MBRX)- Rodman & Renshaw Mkt Perform » Mkt Outperform
Downgrades
Matsushita Elec (MC)- Citigroup Buy » Hold
Cinemark (CNK)- JP Morgan Overweight » Neutral
Garmin (GRMN)- Soleil Buy » Hold
LifeCell (LIFC)- Piper Jaffray Buy » Neutral
Infineon (IFX)- Credit Suisse Outperform » Neutral
Novartis AG (NVS)- Bear Stearns Outperform » Peer Perform
Washington Mutual ( WM)- Keefe Bruyette Mkt Perform » Underperform
Apple (AAPL)- Morgan Keegan Mkt Perform » Underperform
Flowserve (FLS)- Robert W. Baird Outperform » Neutral
Disclosure (“none” means no position):
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.
Upgrades
Nutrisystem (NTRI)- Boenning & Scattergood Market Underperform » Market Perform
Energy Transfer (ETP)- UBS Neutral » Buy
Pacific Sunwear (PSUN)- Wachovia Mkt Perform » Outperform
NuStar GP Hldgs (NSH)- Citigroup Hold » Buy
Enterprise GP Holdings (EPE)- Citigroup Hold » Buy
Corning (GLW)- RBC Capital Mkts Sector Perform » Outperform
Intevac (IVAC)- Brean Murray Hold » Buy
Kinetic Concepts (KCI)- Wachovia Mkt Perform » Outperform
Seaspan (SSW)- Wachovia Mkt Perform » Outperform
MetroPCS (PCS)- Wachovia Mkt Perform » Outperform
Metabasis Therapeutics (MBRX)- Rodman & Renshaw Mkt Perform » Mkt Outperform
Downgrades
Matsushita Elec (MC)- Citigroup Buy » Hold
Cinemark (CNK)- JP Morgan Overweight » Neutral
Garmin (GRMN)- Soleil Buy » Hold
LifeCell (LIFC)- Piper Jaffray Buy » Neutral
Infineon (IFX)- Credit Suisse Outperform » Neutral
Novartis AG (NVS)- Bear Stearns Outperform » Peer Perform
Washington Mutual ( WM)- Keefe Bruyette Mkt Perform » Underperform
Apple (AAPL)- Morgan Keegan Mkt Perform » Underperform
Flowserve (FLS)- Robert W. Baird Outperform » Neutral
Disclosure (“none” means no position):
Visit the ValuePlays Bookstore for Great Investing Books
This work is licensed under a Creative Commons Attribution 2.5 License.